
Our website is temporarily unavailable while essential maintenance is carried out.
To contact Coombes and Wright Mortgage Solutions, please call 01707 817323 or email enquiries@cwmortgagesolutions.co.uk
Mortgage & Protection Questions & Glossary
Find answers to common mortgage and protection questions and explore our useful glossary of industry terms. Drawing on more than 180 years of combined experience, we share expert insights to help you navigate your property and protection journey with confidence.
Our Commitment to You:
Coombes & Wright Mortgage Solutions provide local, flexible and friendly mortgage and protection advice, making the process as straightforward as possible from start to finish.
We pledge to:
Simplify your mortgage and protection journey from initial enquiry to completion.
Search over 65 lenders to find suitable products for your needs.
Clearly explain your options, the process and any costs involved.
Compare protection policies from a range of insurers.
Offer free, no-obligation consultations in person, by phone or via video call.
Manage the entire application process, including paperwork and administration.
Liaise with lenders, solicitors, estate agents and housebuilders on your behalf.
Keep you updated throughout, helping to ensure a smooth and stress-free experience.
What Should I Expect from My Mortgage & Protection Adviser?
We take the time to understand your circumstances, goals and future plans before providing tailored mortgage and protection advice.
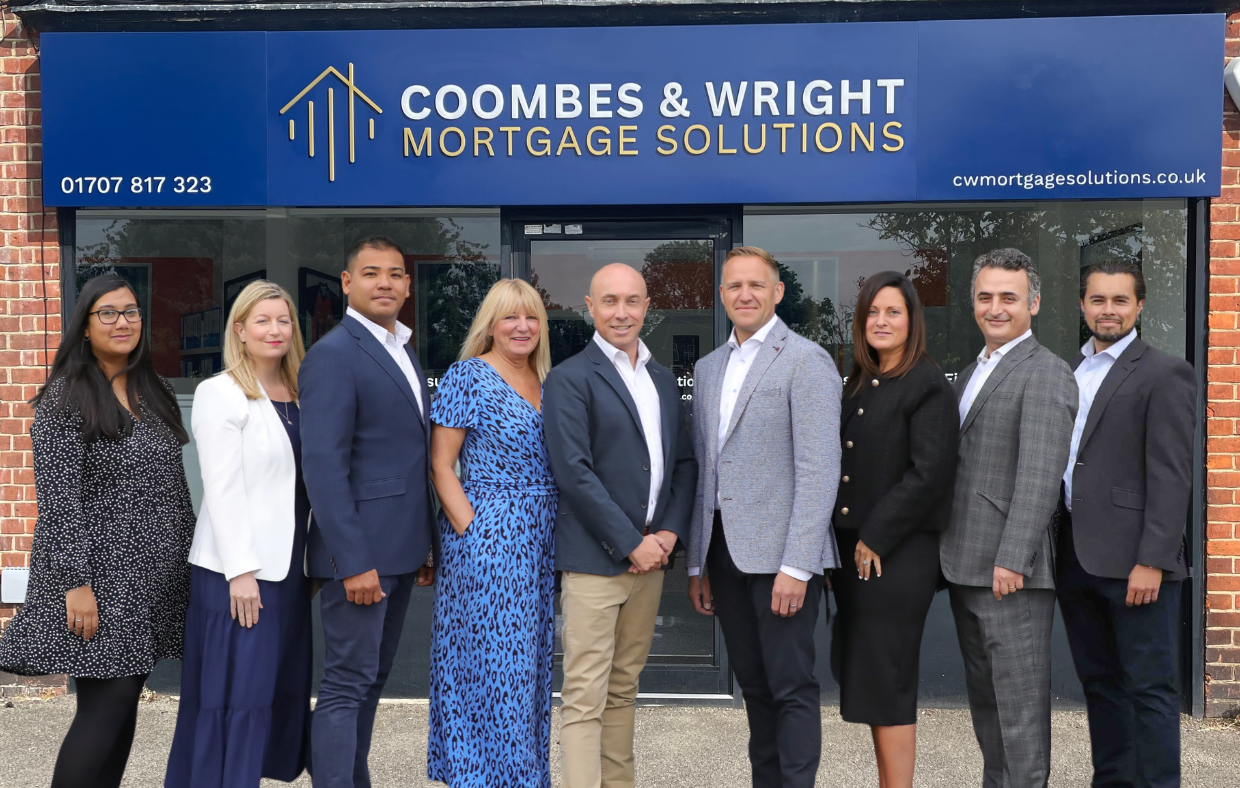
With advisers based across Hertfordshire, Kent and London, we combine local knowledge with the ability to support clients throughout the UK.
Our experienced team stays up to date with the latest mortgage products, lender criteria and protection solutions, ensuring you receive clear, informed advice at every stage. Supported by our dedicated Client Support Team, we'll guide your application from enquiry to completion, keeping the process smooth, straightforward and stress-free.
-
To recommend suitable mortgage options, we'll need details about your income, employment, outgoings, deposit, credit history and personal circumstances. This helps us assess affordability and find the right solution for you.
-
A mortgage broker or mortgage advisor acts as the link between you and a lender, helping you find and arrange a suitable mortgage. We compare a wide range of products, including exclusive deals, to help secure the right mortgage for your needs.
-
The most suitable mortgage depends on your circumstances and goals. With options including fixed, tracker, variable, offset and flexible mortgages, we'll explain the choices and recommend the most appropriate solution for you.
-
A purchase mortgage is used to buy a property. A remortgage involves switching your existing mortgage, often to secure a better rate, release equity, fund home improvements or review your current arrangements.
-
The amount you can borrow is based on factors such as your income, outgoings, credit history, deposit and overall affordability. As lender criteria vary, we'll help you understand your borrowing potential and find suitable options.
See our handy Mortgage Calculator to get a rough guide on your borrowing limits.
-
Income Protection provides a monthly income if you're unable to work due to illness or injury. Critical Illness Cover pays a tax-free lump sum if you're diagnosed with a specified serious illness covered by the policy.
-
Life insurance isn't usually a requirement for obtaining a mortgage, but it can provide valuable financial protection for your family by helping cover mortgage payments or outstanding debt should the worst happen.
Mortgage & Protection Glossary
We have created the following glossary of mortgage and protection terms, words, products and phrases to help you understand your options. If you have any questions, please contact our team.
Life Insurance – insurance that pays out a sum of money either on the death of the insured person or after a set period.
Family Income Benefit – is a type of term life insurance policy that will give your family regular financial support if you die or are diagnosed with a terminal illness.
Critical Illness Cover – provides you with a lump sum of money if you are diagnosed with certain illnesses or disabilities.
Income Protection – pays you a regular income if you can’t work because of sickness or disability and continues until you return to paid work.
Mortgage Protection – is a type of policy that helps to pay your monthly mortgage repayments if you can’t work due to illness or a serious injury.
Private Medical Insurance – is designed to cover the cost of private medical treatment for ‘acute conditions’ that start after your policy begins.
Rent Protection – protects landlords against loss of income if a tenant falls behind or defaults on rent payments.
Limited Company Relevant Life Insurance – is designed to allow employers to provide an individual death in service benefit for an employee in a tax-efficient way, both for the employer, employee and the employee’s beneficiaries.
Equity Release – the use of financial arrangements that provide the owner of a house or other property with funds derived from the value of the property while enabling them to continue using it.
First-time Buyer Mortgages – if you’ve never owned a home previously, either in the UK or abroad. You only own, or have owned, a commercial property.
Remortgages – when you move your mortgage on your existing property, from one lender to another.
Buy-to-Let Schemes – is for people looking to buy a property to rent out, rather than live in it. Most Buy to Let mortgages are interest only. This means that the monthly repayments will only pay off the interest, not the amount owed on the mortgage.
Government-backed 5% Deposit Schemes – The scheme means more 95% loan-to- value (5% deposit) mortgages. Under the scheme, First-time buyers, home movers and previous homeowners with a 5% deposit have access to 95% loan-to-value mortgages (meaning the loan is for 95% of the property’s value).
Parent/Family Assist Mortgages – will allow your family members, and sometimes friends, to help you buy a home.
Home Improvement Financing – is a type of unsecured personal loan – allowing you to borrow a lump sum to help fund renovations or refurbishments.
Holiday Lets – this is where a property is let for the purpose of a holiday only. Generally, this will be where the guest has a main home elsewhere.
Lifetime Mortgages to release equity for over 55’s* (via referral) - Involves securing a loan against your property (if you take out a lifetime mortgage) or selling a share of your home to the equity release provider.
2nd Charge Lending (via referral) – can be an ideal solution for fund raising when a remortgage or further advance are not viable.
HMO Mortgages – is a type of specialist mortgage that is used to finance house in multiple occupations.
Bridging Finance – is a short-term loan used until a person or company secures permanent financing or pays an existing obligation.
Right-to-Buy – allows most council tenants to buy their council home at a discount.
Help-to-Buy – is a government scheme to help First-time buyers get a property with just a 5% deposit.
Shared Ownership / Shared Equity – involves buying a share of a property and paying rent on the rest. Shared equity involves paying a low property deposit, using an equity loan for a percentage of the property’s value, and getting a mortgage for the remaining amount.
Debt Consolidation – when you take out a single, new loan to pay of several existing debts. This can be a good way of taking control of your finances, but you need to be careful.
Adverse Credit / Poor Credit Mortgages – mortgages designed for people with poor credit, and some lenders specialise in offering these. These are known as bad credit mortgages, adverse credit mortgages, or sub-prime mortgages.
Rate Switch Comparison (up to 6 months before current deal ending) – is the process of switching to a better rate with your existing lender.
Commercial Lending (via referral) – is a debt-based funding arrangement between a business and a financial institution such as a bank.
Retirement Interest-Only Mortgage – is available to people over 55. It’s a loan secured against your home. You pay the interest each month, which means the amount you owe doesn’t increase over time. You can use it for most purposes (including paying off an existing mortgage).
Get in touch with us today to learn how we can provide you with flexible and friendly mortgage and protection advice.
Book your free, no-obligation initial consultation
We'll understand your circumstances and objectives
We compare suitable options from our lender panel
We manage the application process
We support you through to completion
How it works
Ready to take the next step?
Whether you're buying your first home, remortgaging, investing in property or looking for protection advice, our qualified advisers are here to help.
Book your free, no-obligation consultation today.
Connect with Us · Connect with Us · Connect with Us ·
Connect with Us · Connect with Us · Connect with Us ·
Follow Coombes & Wright Mortgage Solutions on social media for all our latest industry news, advice and competitions.
IMPORTANT INFORMATION THINK CAREFULLY BEFORE SECURING OTHER DEBTS AGAINST YOUR HOME. YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
If you are experiencing financial difficulty and struggling to make repayments, then you can contact your lender who may be able to help taking account of your individual circumstances. You may want to contact one of the free impartial money guidance and debt advice services, such as StepChange, Citizens Advice, or Turn2Us.
You can make a complaint to our network Sesame. Please contact them on the details below:
Write to: The Customer Relations Department, Sesame Limited, Fourth Floor, Jackson House, Sibson Road, Sale, M33 7RR.
Email: CustomerRelations@sbg.co.uk
Telephone: 0345 0456 800 (Mon-Fri 9 am to 5 pm)